Searches for Form 10F spike whenever a payer in India stops a payment and asks for it. The form has a new number now, but the questions are the same: do I need it, what goes in it, and how do I file it from abroad?
What is Form 10F?
What is Form 10F? It is the non-resident's own online declaration for claiming a treaty rate. Under the Income-tax Act 2025 it is Form 41. People still search for the income tax Form 10F, and the 10F form under its old name, so this post uses both. Form 10F India filings now go through Form 41 on the e-Filing portal. It is required even where you already hold a tax residency certificate. You give it, with the certificate, to the payer before tax is deducted.
Do you need it?
Yes, whenever you claim a treaty rate on income from India. Section 159(8) of the Income-tax Act 2025 (old Sections 90(5) and 90A(5)) asks for it, and the form sits under Rule 75 of the Income-tax Rules 2026 (old Rule 21AB). It is required even where the certificate of residence has already been issued. The certificate proves residence. Form 41 is your own declaration to India. For the certificate itself, read Tax Residency Certificate for DTAA: Who Issues It and What India Needs.
It does not help in four cases:
- •
No TRC: the treaty benefit is not available, so Form 41 alone does not unlock it.
- •
No treaty: there is nothing to claim.
- •
A resident: the form is for non-residents.
- •
Anti-abuse tests: the form is a declaration, not proof of substance.
What goes in the form
The form asks for the particulars below, and you attach the TRC. Each cell shows what a certificate usually carries, so you can see what to add yourself.
| Particular | Usually on the TRC? | If the TRC lacks it |
|---|---|---|
| Name and status (individual, company, firm, other) | Name yes; status sometimes | State it in the form |
| Nationality or country of incorporation | Sometimes | State it in the form |
| Country of residence and address there | Usually | State the address in the form |
| Tax identification number | Often | Give it in the form; for countries without one, use a unique identification number such as the Emirates ID |
| Tax year | Period on the TRC | Choose the year when you open the form |
| Communication address, email, designation, PAN (optional) | No | Fill in the form |
This is a field guide, not a filled sample.
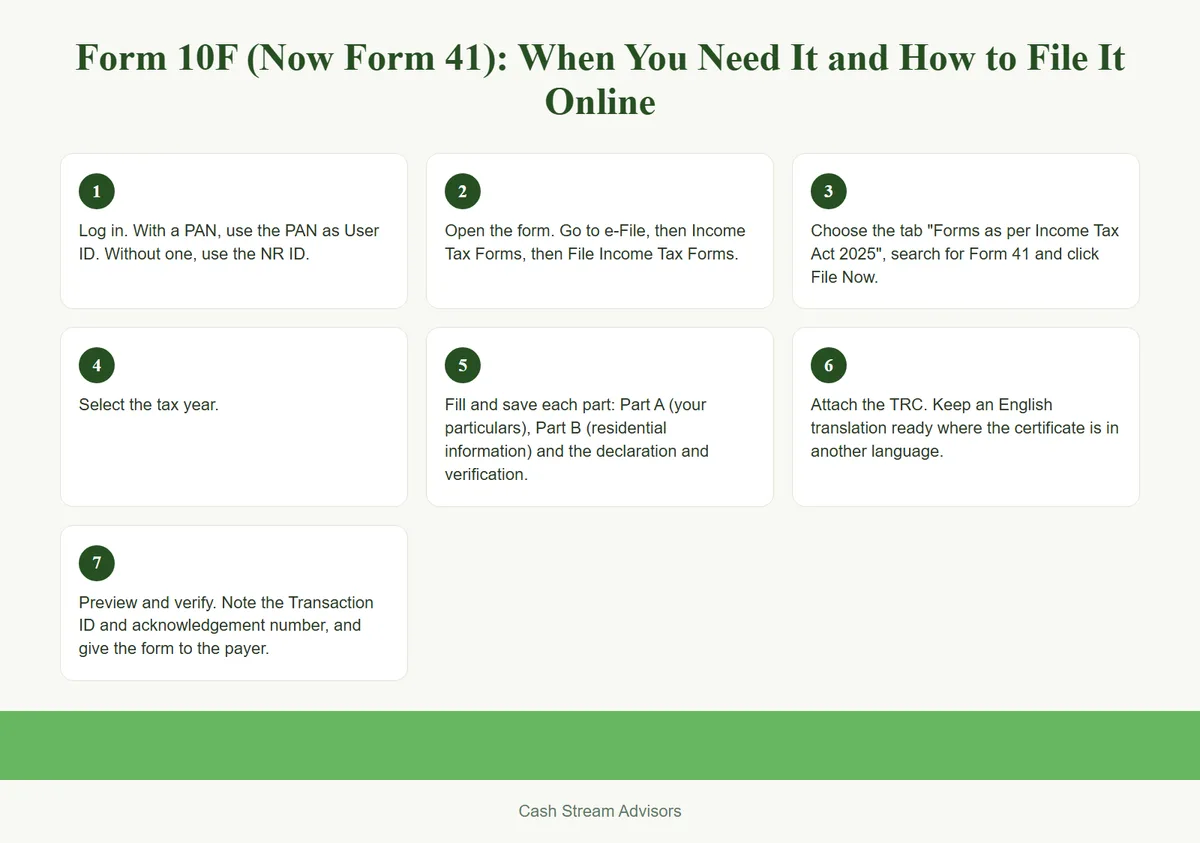
How to file Form 41 (Form 10F) online
Filing is online only, on the Income Tax e-Filing portal.
- 1
Log in. With a PAN, use the PAN as User ID. Without one, use the NR ID.
- 2
Open the form. Go to e-File, then Income Tax Forms, then File Income Tax Forms.
- 3
Choose the tab "Forms as per Income Tax Act 2025", search for Form 41 and click File Now.
- 4
Select the tax year.
- 5
Fill and save each part: Part A (your particulars), Part B (residential information) and the declaration and verification.
- 6
Attach the TRC. Keep an English translation ready where the certificate is in another language.
- 7
Preview and verify. Note the Transaction ID and acknowledgement number, and give the form to the payer.
With a PAN login, verification can use a digital signature certificate (DSC), which is the easiest route and is also useful when you file the income tax return. With an NR ID login, verification is by OTP. The menu names above follow the Department's user manual, so check them against the live portal when you file.
The form has no "no permanent establishment" declaration. Payers often ask for it separately, so keep a signed declaration ready.
If you have no PAN
A non-resident who has no PAN, and is not required to have one, can still file. Register on the portal under the separate non-resident category, log in with the NR ID, and verify with OTPs sent to your registered email and mobile. PAN is optional in Part A. You still need your tax identification number from the country of residence and the certificate. The relaxation that allowed paper filing ended on 30 September 2023.
Timing: before the payer deducts tax
Give the certificate and Form 41 to the payer before the payment is made. Without a valid electronically filed Form 41, the treaty benefit is not available and tax is deducted at the applicable rate. If tax has already been deducted, the excess comes back through the return of income. That takes longer and needs a clean record trail.
For payers: what to check before applying the treaty rate
- 1
The TRC is correct, valid for the year of payment, and in the name of the payee.
- 2
The TRC is in English, or comes with an English translation.
- 3
Form 41 is filed, and its particulars match the TRC (name, tax identification number, tax year).
- 4
A no-PE declaration has been received from the payee.
- 5
Substance in the country of residence has been reviewed, not just the paper.
- 6
Where the payer asks for it, a certified copy from the payee's auditor confirms the payee's tax residency.
The paper does not guarantee the rate. For the payer position, speak to us about the Withholding Tax Advisory service.
What goes wrong
Form 41 is not rejected when it is filed. The problems come later, when the filing is picked up in an assessment. If the original filing was wrong, it causes a great deal of trouble. Five causes, with fixes:
- 1
TRC does not match the form. Fix: check name, tax identification number and year before you file.
- 2
TRC in another language. Fix: attach an English translation.
- 3
No no-PE declaration. Fix: obtain it from the payee before payment.
- 4
Residence not backed by substance. Fix: review where the company is managed and operates before the rate is applied.
- 5
An incorrect original filing. The form cannot be edited once acknowledged. Fix: get it right the first time, and speak to an adviser if you find a mistake after filing.
Validity and renewal
File Form 41 for each tax year in which you claim the treaty, with a certificate valid for that year. A Form 10F filed for an earlier period still stands for that period. File again when the TRC is renewed. Message us on WhatsApp if the year or the certificate does not match.
Talk to an advisor
If the year, the certificate or the particulars do not match, message us on WhatsApp, book a consultation, or write to contact@cashstreamadvisors.com.
This Insights article is general information, not advice on a specific transaction. Read our disclaimer and regulatory compliance pages.
DTAA Advisory service
INSIGHTSWhat Is DTAA? How the Double Tax Avoidance Agreement Works in India
INSIGHTSTax Residency Certificate for DTAA: Who Issues It and What India Needs
INSIGHTSIndia-USA DTAA: Treaty Rates, Forms and How to Claim Them
SERVICEAll insights
ABOUTAbout Cash Stream Advisors
CONTACTContact us
Official references
DTAA Advisory
Treaty relief and TRC compliance for cross-border income., handled so it does not become the subject of your next article.